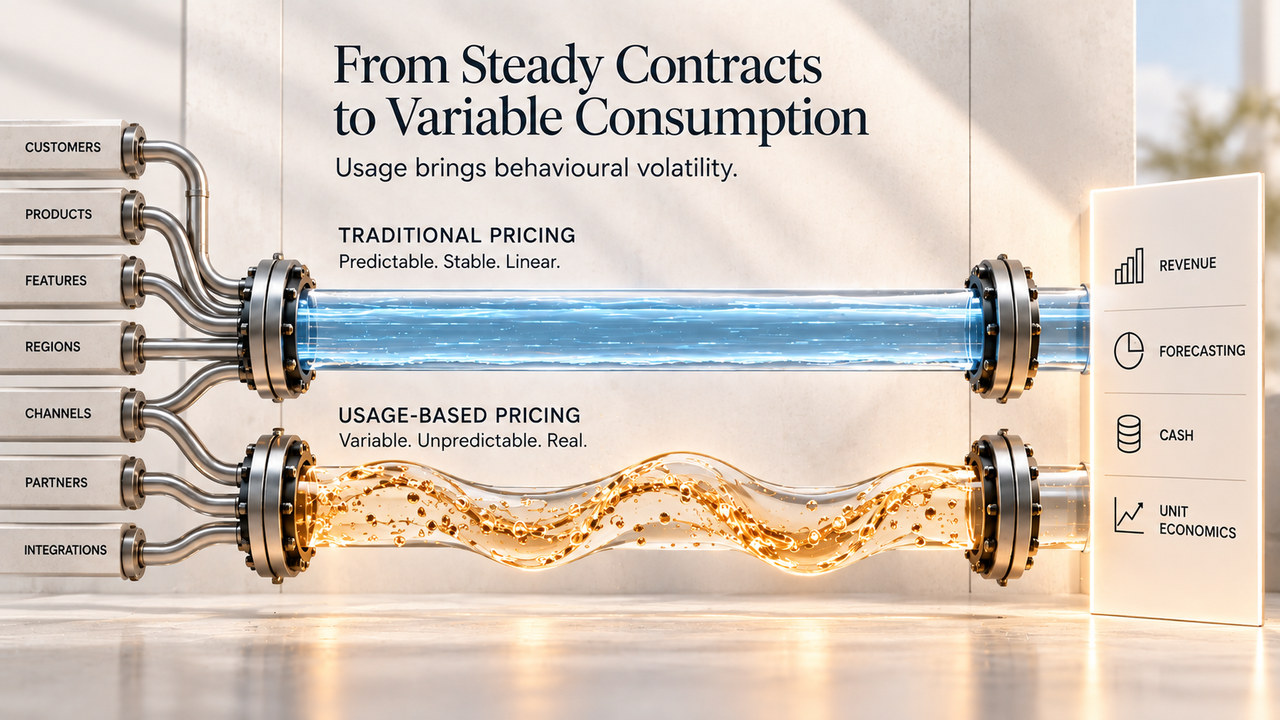
Usage-based pricing shifts finance from contract certainty to behavioral volatility. Revenue is recognized as consumption occurs, so metering must be accurate enough to withstand audit. Forecasts move from contracted waterfalls to driver-based models built on cohort consumption curves. Cash timing decouples from bookings as billing shifts to arrears, turning deferred revenue from a financing source into a working capital gap. Margins must be managed per unit of usage because cost to serve scales with the same driver as revenue. The systems that make consumption pricing safe (auditable metering, behavioral forecasting, unit margin discipline) belong in place before launch.
Usage-based pricing gets approved as a growth decision and lands as a finance rebuild. When revenue moves from contracted subscriptions to metered consumption, the finance function inherits volatility it was never designed to carry: revenue you cannot recognize until you can prove what was delivered, forecasts that rest on customer behavior instead of signed contracts, cash that arrives on a different clock than bookings, and unit economics that shift with every workload. The fix is sequencing. Build four things before launch: metering an auditor would accept, a driver-based forecast, cohort consumption curves, and margin discipline per unit of usage. I spent years taking flexible-consumption models to market for Cisco Capital across EMEA and APJC, and the pattern was consistent: pricing was the easy part.
What breaks in finance when pricing becomes usage-based?
Four things break at once: revenue recognition, forecasting, cash timing, and unit economics. Subscription finance is built on anchors. A signed contract gives you a known price, a known term, and a known billing schedule, and the whole finance stack leans on those three certainties. Usage pricing removes them in one move. The amount is now variable, the effective term is however long the customer keeps consuming, and the invoice is a function of behavior you do not control.
Most operators I speak with underestimate how far the damage travels. It reaches revenue recognition, because you can only recognize what you can measure and defend. It reaches the forecast, because pipeline and renewals no longer describe next quarter. It reaches the cash flow statement, because billing in arrears reverses the working capital logic of prepaid SaaS. And it reaches the board deck, because ARR, the one number everyone trusted, stops meaning what it used to mean.
Why is metering a finance system before it is a product feature?
Because every downstream number inherits the meter's accuracy: recognized revenue, invoices, forecasts, unit margins, even the board's growth narrative. Under both US GAAP and IFRS, usage revenue is generally recognized as the usage occurs. That sounds like a simplification until you sit with what it demands: evidence that the usage happened, when it happened, at what rate, and under which contract's terms. Your meter is now the source document for revenue. Treat it with the seriousness you would give the general ledger.
Metering built for product dashboards rarely survives that standard. Product telemetry tolerates sampling, gaps, and retroactive fixes; metering that feeds revenue has a stricter contract. Before launch, I want to see completeness checks (every billable event captured exactly once), immutability (no silent restatement of history), reconciliation between the meter, the rating engine, and the invoice, and the ability to replay any customer's month from raw events. The test I use is simple. Would you let an external auditor sample it? If the answer makes you uncomfortable, you've found your critical path, and it is an engineering project with a finance owner.
If an auditor would not trust your meter, neither should your board.
How do you forecast revenue that depends on behavior instead of contracts?
You replace the bookings waterfall with a driver-based model, and you build it on cohort consumption curves. A subscription forecast is arithmetic on contracts: opening base, plus new bookings, plus expansion, less churn. A consumption forecast is a behavioral model: how many active customers, consuming how much, at what effective rate, and how each of those drivers is trending by cohort.
Cohort consumption curves are the core asset. Group customers by start period, segment, and workload type, then track how their usage ramps month by month. The curves tell you what a newly landed customer is worth over the next 18 months, where consumption plateaus, and which cohorts are still expanding long after the ramp should have flattened. They also give you leading indicators that contracts never provided: a slowdown in usage growth surfaces in the data months before it would ever surface in a renewal conversation.
Two disciplines keep the model honest. First, forecast in ranges, because point estimates on behavioral drivers are false precision; give the board a corridor and the assumptions that move it. Second, keep the drivers few and observable. If your forecast rests on more than a handful of drivers, you have built a spreadsheet you cannot interrogate. This is also where team capability bites: a finance function that lives in the rear-view mirror cannot run a behavioral forecast, a gap I have mapped in the finance function maturity ladder.
Why does cash timing decouple from bookings in consumption models?
Because consumption is typically billed in arrears, and arrears billing reverses the cash advantage subscription companies are built on. Annual prepay collects cash before the service is delivered, so deferred revenue acts as free financing for growth. Move the same customer to metered billing and the sequence flips: you deliver first, invoice at month end, and collect on the customer's payment terms. Working capital swings from a source of cash to a use of it, at exactly the moment revenue becomes harder to predict.
Hybrid structures soften this but add their own accounting weather. Committed-spend contracts with drawdown bring cash forward again, then raise new questions: how consumption draws against the commitment, what happens to unconsumed balances, and how breakage is treated. Collections change character too. Variable invoices invite disputes, and every dispute in a consumption business is really a metering dispute, which is one more reason the meter must be defensible. Model the transition explicitly: as legacy prepaid contracts run off and metered billing ramps, most companies cross a cash trough. Boards forgive a trough they were told about; a trough they discover costs you credibility.
What margin discipline does consumption pricing demand?
Margin per unit of usage, tracked continuously, because your cost to serve now scales with the same driver as your revenue. Subscription gross margin is comparatively stable; consumption gross margin is a moving portfolio. Every workload has its own cost profile, every customer mixes workloads differently, and a healthy headline margin can hide customers you are paying to serve.
The discipline has three parts. Know your cost per metered unit, by product and by infrastructure tier, and refresh it as your vendors reprice. Set price floors from those cost curves, so discounting authority has a boundary anchored in unit economics. And review margin at the cohort and account level on a fixed cadence, because deterioration in a consumption business compounds while everyone is watching the growth number.
Portfolio discipline is old finance craft applied to a new object. As Region CFO for Cisco MEA (2015 to 2022, a $1B P&L), I ended a recurring discount debate on our Turkish telecom accounts by mapping the region's key operator accounts on a BCG growth and profitability matrix. The Turkish accounts were Dogs. Their margin was redeployed to Stars and Question Marks, and the debate ended in one meeting. Consumption pricing asks for the same move at a finer grain: workloads and cohorts on the matrix, and the honesty to act on where they land.
What should you build before you launch usage-based pricing?
Six things, and they belong on the critical path with engineering, ahead of the pricing announcement.
- Finance-grade metering. Complete, immutable, reconciled to the invoice, replayable from raw events. If the auditor test fails, the launch date moves.
- A driver-based forecast. Few drivers, all observable, presented as ranges with named assumptions.
- Cohort consumption curves. Even a short history beats none; start instrumenting cohorts in the beta, before general availability.
- A unit margin model. Cost per metered unit by product and tier, price floors derived from it, discount authority bounded by it.
- Billing and collections redesign. Arrears invoicing, dispute handling that can reference the meter, and a working capital plan for the transition trough.
- A new board metric set. Annualized run-rate revenue on trailing consumption, net revenue retention measured on consumption cohorts, committed versus consumed spend, and margin per unit, agreed with the board before the first volatile quarter, never during it.
Sequencing is the whole game. Every one of these is cheaper and calmer to build before launch; every one becomes a crisis project after. In my experience the build takes about 100 days for a company with clean data, longer where the meter has to be engineered from scratch, and it needs a senior finance owner rather than a committee. If nobody on your finance team can carry it, that's a signal worth reading in its own right; I have written about that decision in when to bring in CFO-level capability.
This transition sits exactly where I spent the last stretch of my corporate career. After seven years as Region CFO, I led flexible-consumption go-to-market for Cisco Capital across EMEA and APJC, taking pay-as-you-go and pay-as-you-grow models into markets that priced everything by contract. Third Horizon Capital Advisory now does this work for founders and boards: pressure-testing the metering plan, building the driver-based forecast and cohort curves, and setting the margin guardrails, as part of a broader strategic financial planning engagement. It usually starts with a three-week diagnostic, and I lead every engagement personally.
If usage-based pricing is on your roadmap for the next two quarters, let's talk before the launch date is set.
Kamran Habibollah is the founder of Third Horizon Capital Advisory, a senior financial advisory firm in Dubai serving founders, CEOs, CFOs, and boards across the GCC, the UK, and Europe.
Kamran Habibollah
Founder & Principal, Third Horizon22 years across technology, telecom, and finance at Siemens, Nokia, and Cisco, including seven years as Region CFO for Cisco MEA with a $1B P&L. He advises founders, CEOs, and boards on capital, transactions, and finance leadership from Dubai.
More about Kamran →