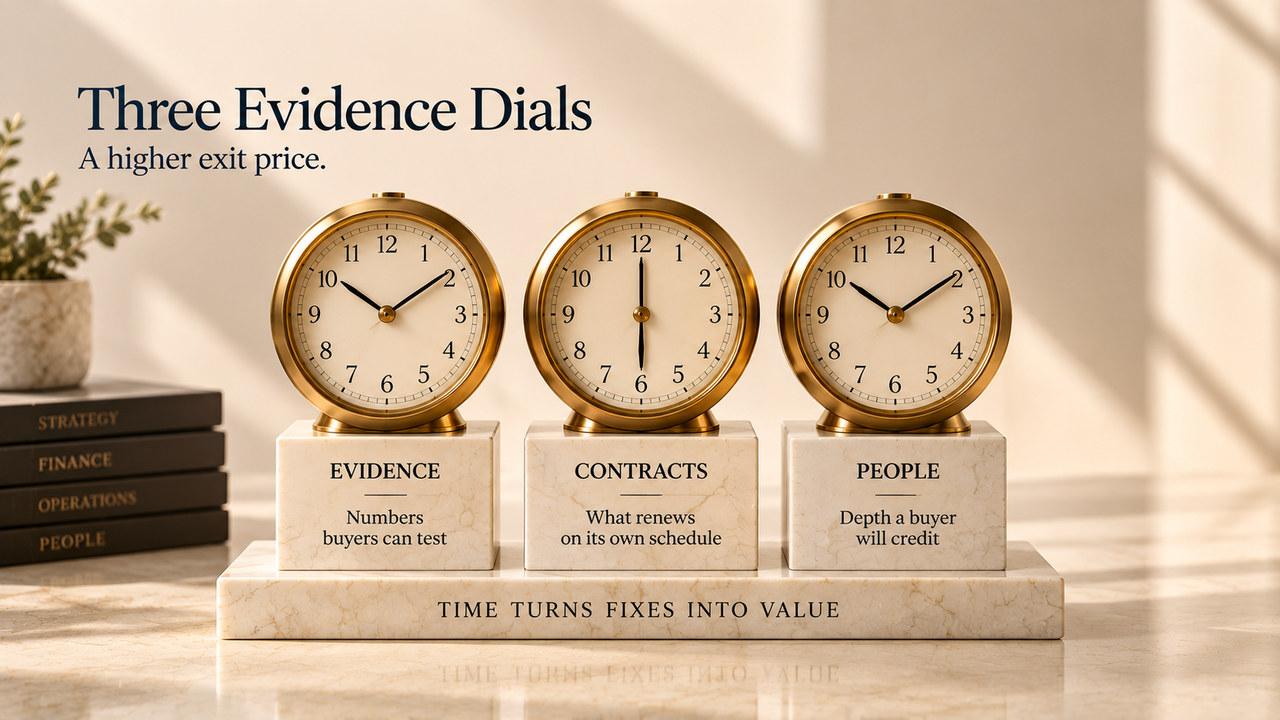
Exit preparation takes about 18 months because the improvements that raise valuation must become evidence a buyer can test, and evidence accumulates only through elapsed time. Revenue recognition cleanups need audited quarters behind them. Customer concentration improves only through renewal cycles and new revenue. Management depth is credited once a leader has roughly a year in seat. Sellers should plan around three clocks that cannot be compressed, covering evidence, contracts, and people, then sequence the work across six quarters: diagnose first, fix and let the fixes generate reported history, then run the process from proof rather than promises.
The price you get for your company is mostly set before the sale process begins. By the time an advisor builds the materials and buyers start asking questions, they're pricing what already exists: the quarters you've reported, the contracts already signed, the team already in place. That is why preparing a business for exit takes about 18 months. Most founders can list the fixes that would move their valuation in one afternoon. Evidencing those fixes is the slow part, because the evidence a buyer will pay for only accumulates in real time.
A cleaned-up revenue recognition policy means little until audited quarters sit behind it. Customer concentration improves only as renewal cycles pass. A strong hire starts to count once they've run their function for a full year. Time is the raw material of exit value, and it can't be bought back.
Why does exit readiness take 18 months?
Because valuation rests on evidence, and the evidence buyers accept can only accumulate through elapsed time. Eighteen months is roughly six quarters: two to diagnose and fix, two to let the fixes generate reportable history, and two to run the process itself while the business keeps performing. Compress any of those and something gives. Compress the first and you fix the wrong things. Compress the middle and your improvements exist only as claims. Compress the last and you negotiate under time pressure, which buyers sense and price.
Most founders I speak with begin thinking seriously about an exit when an inbound approach lands, which means the timeline is already someone else's. Sellers who do well work backward from a target window and manage three clocks that started running long before anyone noticed: the evidence clock, the contract clock, and the people clock. None of the three can be sped up with money or effort. You can only start them earlier.
Time is the one input to your exit price that can't be bought later.
The evidence clock: numbers buyers can test
The evidence clock governs everything a diligence team will test against your reported history, and it's the slowest of the three. Change your revenue recognition policy today and a buyer sees one clean quarter at best; they'll want to watch the new policy hold across several reporting periods, ideally under audit, before they price it as real. The same applies to gross margin definitions, the way you count recurring revenue, cohort and retention data, and the bridge between your management accounts and your statutory numbers.
Diligence teams rebuild your numbers from source. Every definition you've been casual about internally will be reconstructed by someone whose job is to find the gap, and a gap discovered deep into a live process costs far more than the same gap fixed 18 months earlier. If your numbers have never been pulled apart by an outsider, commission that exercise first. The discipline is the same one I describe in investor readiness: numbers that survive someone else's model, definitions that hold under hostile reading, and a forecast you've actually hit.
The contract clock: what renews on its own schedule
The contract clock governs everything that only changes when a counterparty signs, and counterparties sign when their own calendars say so. Customer concentration is the obvious case. If one customer carries an outsized share of your revenue, dilution comes from new revenue and passed renewal cycles, and both take quarters to accumulate. If your key contracts renew annually, you get exactly one opportunity per contract per year to extend the term, tighten assignment language, or convert an informal arrangement into paper a buyer can rely on.
Change-of-control clauses deserve their own pass. Buyers read your contracts as they stand on signing day, and a key agreement that terminates on a change of ownership is a price reduction waiting to be discovered. So are month-to-month arrangements with strategic customers, expired framework agreements everyone honors out of habit, and side letters nobody filed. Timing matters here too. Pushing customers onto longer terms three months before a process looks defensive and invites questions. The same conversations held 18 months out read as ordinary commercial discipline.
The people clock: depth a buyer will credit
The people clock governs how much of the business a buyer believes runs without you, and that belief takes about a year in seat to form. A finance leader hired a quarter before launch is a promise. One who has closed four quarters, presented to your board, and held a forecast is evidence. Buyers apply the same test to commercial leadership: who owns the top customer relationships, and what happens to them when your name comes off the door.
This is the clock founders underestimate most, because they experience their team from the inside and fill every gap reflexively. A buyer experiences your team from the outside, across a handful of management presentations, and prices exactly what they see. Founder dependence is among the most common discounts in mid-market deals. It's also among the most fixable, provided the fixing starts early enough for the new depth to own a track record by the time anyone is watching.
A quarter-by-quarter preparation sequence
Work backward from your target window in six quarters and put the slowest fixes first. Treat what follows as a checklist if that helps, but respect the ordering; the sequence exists because of the clocks.
- Quarters six and five (18 to 12 months out): diagnose. Commission a diligence-grade review of revenue recognition, margin definitions, and reporting quality. Start or upgrade the audit if your buyer universe will expect one. Map every material contract with its renewal date, term, and change-of-control language. Name the management gaps honestly and open the searches. Decide the equity story you're selling, because it determines which fixes matter most.
- Quarters four and three (12 to 6 months out): fix, then let it season. New accounting policies run through live reported periods. Renewals get negotiated as they fall due, with term and assignment in mind. New leaders take visible ownership, with their names on the numbers in front of your board. Sell-side quality of earnings preparation starts here, while there's still time to act on what it finds.
- Quarters two and one (6 months to launch): package and run. Engage the sell-side advisor, build the materials from evidence that now exists, and protect the operating rhythm, because the most expensive event in any process is a missed forecast mid-deal, and the credibility that prevents one was built in the quarters before.
What do buyers pay for, and what do they discount?
Buyers pay premiums for predictability and discount whatever they must take on faith. Predictability means recurring revenue with demonstrated renewal history, audited numbers that reconcile cleanly to management accounts, contracts that transfer, and a leadership team with results attached to their names. Faith means adjusted earnings carrying a long tail of add-backs, policies changed on the eve of a process, and revenue whose durability you can only assert verbally.
Buyers will also triage your revenue, whether or not you've done it first. As Region CFO for Cisco in the Middle East and Africa, I ended a recurring discount debate on our Turkish telecom accounts by mapping the region's key operator accounts on a BCG growth and profitability matrix. The Turkish accounts were Dogs. We redeployed that margin to the Stars and Question Marks, and the argument did not survive the chart. Diligence teams run the same exercise on your customer base. Do the triage first and you control the story and the remediation. Wait, and you meet their version of it in the price.
One more angle worth thinking through: if your likely buyer is private equity, read what the first 100 days of PE ownership demand of a finance function. The function that survives that period is the one you should be building 18 months before the sale anyway. Preparation for a buyer and value creation for yourself converge on the same work.
Third Horizon Capital Advisory runs exit readiness as senior work, with no junior staff involved. A three-week diagnostic maps all three clocks against your target window and tells you what is genuinely fixable in the time you have. Fixed-fee readiness programs close the gaps, and M&A advisory and transaction support carries through the process itself. Every engagement is led by me personally, under NDA by default.
If an exit sits anywhere in your next two or three years, the valuable conversation is the one that happens now, while all three clocks are still yours to start. Let's talk.
Kamran Habibollah is the founder of Third Horizon Capital Advisory, a senior financial advisory firm in Dubai serving founders, CEOs, CFOs, and boards across the GCC, the UK, and Europe.
Kamran Habibollah
Founder & Principal, Third Horizon22 years across technology, telecom, and finance at Siemens, Nokia, and Cisco, including seven years as Region CFO for Cisco MEA with a $1B P&L. He advises founders, CEOs, and boards on capital, transactions, and finance leadership from Dubai.
More about Kamran →